


TA 62970-03-22 Aura Investments Ltd. v. Director of VAT Tel Aviv Center
The Tel Aviv District Court ruled on 13.2.2025 that the construction of kindergartens, a public parking garage, and a shell for a public building, carried out by a developer on behalf of the municipality in an urban renewal project, constitutes a service subject to VAT. However, the court held that the occupancy permit and areas received through a land readjustment (pooling and reallocation) plan do not constitute consideration, and the assessment for the parking garage was reduced. Attorneys Shlomi Vaknin and Ariel Epstein represented Aura. The judgment is not final: appeals are pending before the Supreme Court.
Court: Tel Aviv-Jaffa District Court, Judge Yardena Seroussi.
Proceeding: TA 62970-03-22, judgment dated 13.2.2025.
Counsel for the Appellant: Adv. Shlomi Vaknin and Adv. Ariel Epstein.
Assessment: Output tax of approximately NIS 5.5 million.
Outcome: The appeal was partially allowed with respect to the amount of the assessment. The VAT on the parking spaces was reduced from NIS 4,203,927 to NIS 1,799,875. No order as to costs.
Status of proceedings: Appeals against the judgment have been filed with the Supreme Court (CA 45772-12-25, Israel Tax Authority v. Aura Investments) and are currently pending.
Get an Initial Legal Consultation
Leave your details and one of our attorneys will get back to you today.
What Were the Facts?
Aura acted as the developer in the "Ono Vaali" urban renewal project in Kiryat Ono. Under a development agreement dated 13.7.2017 with the Kiryat Ono Municipality and the Kiryat Ono Development Company, the company undertook to carry out four tasks at its own expense:
Constructing two new kindergartens to replace two old ones demolished to make way for new residential buildings.
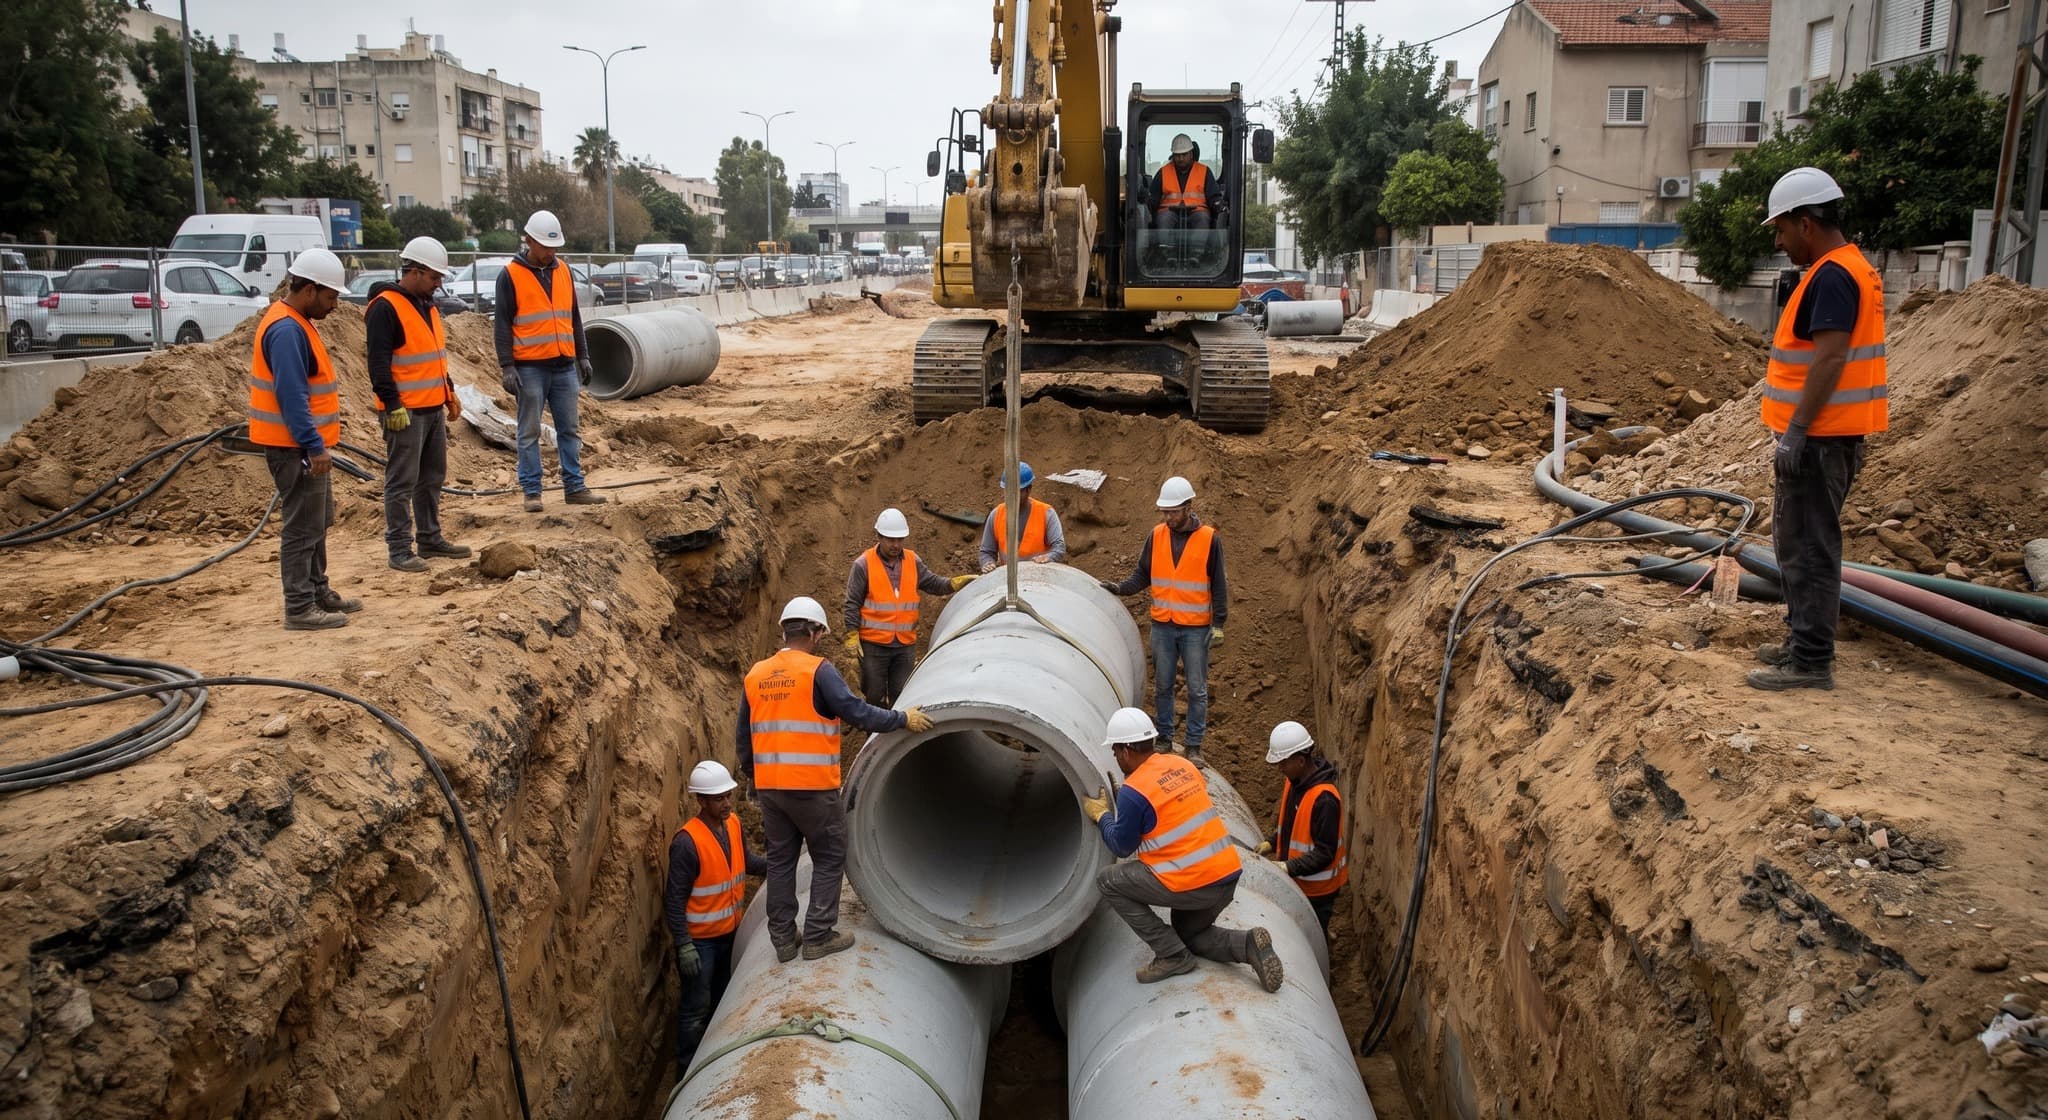
Constructing an underground public parking garage to replace an above-ground parking lot.
Constructing the shell of a public building with an area of 578 sq.m.
Renovating the Rimonim School at a cost of NIS 1 million, due to nuisances caused by the project.
The Director of VAT Tel Aviv Center issued an output tax assessment of approximately NIS 5.5 million. He argued that all the tasks constitute a service to the municipality, and that the consideration includes, among other things, the occupancy permit (Form 4) and the areas the company received under the land readjustment (pooling and reallocation) plan.
What Did the Court Rule?
The Tasks Constitute a Service to the Municipality
The court held that the works were performed "for the benefit of another party," as the municipality desired and benefited from them. The new kindergartens were built to a new standard that includes a safe room (mamad), and the above-ground parking lot was replaced with a modern underground parking garage. Each clause in the development agreement describing the works states that they are carried out "on behalf of the municipality." According to the judgment, the consideration is the municipality's waiver of the payment the developer would otherwise owe for the reconstruction, similar to the rulings in the Hof HaCarmel and Kiryat Sdeh HaTe'ufa cases. The shell of the public building and the school renovation were likewise found to constitute a service to the municipality.
An Open Question: Mere Relocation
The court presented two approaches for a scenario in which a developer merely relocates existing infrastructure — of the same size and to the same standard — for the purposes of its own project. Under the first approach, this does not constitute a service, because the municipality has already fulfilled its obligation and is indifferent to the relocation. Under the second approach, it still constitutes construction that falls under the municipality's responsibility, and the developer acts in a dual capacity. The court did not decide the question, as it found that in this case there was no mere relocation but rather reconstruction to a higher standard.
What Does Not Constitute Consideration
The court rejected the argument that the areas received under the land readjustment (pooling and reallocation) plan constitute consideration. According to uncontested testimony, the extent of public areas remained identical before and after the project, and a pooling and reallocation process does not ordinarily trigger VAT. The occupancy permit likewise does not constitute consideration: according to the judgment, such a determination would mean that "the municipality is trading in the occupancy permit in a manner that is improper and contrary to its purpose" (paragraph 51).
Amount of the Assessment
Regarding the parking garage, the court held that the assessment should be based on 110 parking spaces, rather than 352 as claimed by the Director of VAT, at a rate of 35 sq.m per space and NIS 2,500 per sq.m plus a developer's profit margin of 10%. Regarding the kindergartens, the respondent's representative admitted during the evidentiary hearing that he had erred in his calculation, and the court ruled that the assessment should be computed according to the company's calculation.
What Does This Mean for Developers?
The wording of the development agreement affects the outcome. When it states that the work is performed "on behalf of the municipality," it is difficult to argue that it was carried out solely for the developer's purposes.
When relocating a public building, document the size and standard of both the old and the new structure. The difference between them was central to the ruling.
An occupancy permit (Form 4) does not constitute consideration according to this judgment, and therefore cannot serve as a basis for a VAT assessment.
Review the assessment calculation component by component. In this case, the number of parking spaces and their value were changed by the judgment.
The judgment is under appeal before the Supreme Court, so it is advisable to verify the status of the proceedings before relying on it. For VAT in development agreements, combination transactions, and evacuation-construction (pinui-binui) projects, see VAT in Real Estate Transactions and Urban Renewal.
A district court judgment is not binding on other courts, but it demonstrates how the court examines the argument. For guidance on development agreements and public obligations, see Taxation of Complex Real Estate Transactions. To appeal an assessment, see Objecting to a VAT Assessment. In the media: Article by Adv. Vaknin and Adv. Epstein in Calcalist on the judgment.





